Home › Blog › Are We Buy Houses Companies Legit? Scams and Red Flags
Cash Home Sale GuideAre 'We Buy Houses for Cash' Companies Legit?
Many "we buy houses for cash" companies are legitimate real estate investors who buy homes as-is and close fast. But scams do exist. A real buyer will look at your property, show proof of funds, put the offer in writing, close through a licensed title or escrow company, and never ask you for an upfront fee or to wire money. If anyone pressures you to pay first, walk away.
How legitimate cash-buying companies actually work
A legitimate "we buy houses" company is a direct buyer. It purchases your home with its own funds, usually to renovate and resell or to rent out. You are selling to a real buyer, not listing with an agent and not paying a commission.
- You share basic details about the home (location, condition, situation).
- The buyer evaluates the property in person or by video, looking at condition and needed repairs.
- You get a no-obligation written offer. At Sterling it comes within 12 hours of our call, with the comparable sales behind it.
- Nothing is binding until you sign a written purchase agreement.
- Closing happens through a licensed title or escrow company, on a date you pick, with no repairs, cleaning, or staging required.
The trade-off is price. A cash buyer works backward from what the house will be worth after repairs, then subtracts the repair bill, the months of holding costs, the resale costs and a profit. That's why a cash offer lands below a fixed-up retail price. We walk through how big that gap usually is, and why, in what percentage cash home buyers pay. A fair cash buyer is open about this math and will show you the numbers behind the offer.
Are scams real? Yes, and here's what they look like
The legitimacy of the industry doesn't mean every "we buy houses" sign or cold call is safe. Federal and state regulators keep acting against home-equity and foreclosure-rescue fraud. In one joint action, the CFPB, the FTC and 15 states announced a sweep against foreclosure-relief scammers who used deceptive marketing on distressed homeowners. The patterns below are the ones to know.
- Upfront-fee schemes. A "buyer" asks for a deposit, application, processing, or legal fee before doing anything, then disappears. Real cash buyers never charge the seller a fee to make an offer.
- Equity skimming. Someone offers to "save" your home from foreclosure if you sign over the deed and rent it back. Once they hold the deed, they can sell the home and keep your equity. The FTC's April 2026 alert puts it bluntly: scammers try to get you to transfer the deed, and if you do, you probably won't get it back.
- Overpayment / bad-check fraud. A buyer "accidentally" sends too much, then asks you to wire back the difference. Their original check bounces and your wired money is gone.
- Sight-unseen eagerness. A buyer who never visits, won't take calls, but is desperate to wire a deposit is usually running a fraud.
- Wire-instruction switches. The CFPB warns that scammers suggest last-minute changes to wiring instructions to divert closing money, and says never to follow instructions that arrive by email. Check them in person or with the phone number you agreed on earlier.
See your number. Then decide.
You get a written cash offer within 12 hours of our call, with the comps behind it. No obligation, no pressure.
- No fees or commissions
- Sold as-is
- You pick the date
Red flags that signal a scam
Use this quick checklist. Most cash-buyer scams share the same handful of tells. One or two flags means slow down and verify before you sign or send anything. Several together means walk away.
- Asks you for money up front. A real cash buyer pays you. They never ask you to send an "application," "appraisal," "processing," or "earnest-release" fee to keep the deal moving. All legitimate costs are settled at closing.
- Pressures you to sign immediately. "Sign today or the offer disappears." Constant calls and texts, or a refusal to let you read or keep the contract or talk to a lawyer.
- Won't provide proof of funds. A genuine buyer will hand you a dated bank letter or statement without hesitation. Stalling, excuses, or a blurry screenshot are warning signs.
- An offer that's too good to be true. A wildly high offer is often bait for a later overpayment or fee scam; a shockingly low one paired with foreclosure pressure can be equity skimming.
- Never looks at the property yet still wants to buy.
- Avoids a neutral closing. A buyer who insists on an "in-house" closing and resists a licensed title or escrow company is removing the one party who protects you.
- Sloppy or vague paperwork. No website, no business registration, no company address or phone you can call back, or a contract that leaves the price or terms open.
- Wants payment or refunds by wire, cashier's check, or payment app with urgency.
- Tells you to stop talking to your lender. The FTC lists this as a classic mortgage-relief scam move.
- Asks you to deed over the home before closing or sign documents you don't understand.
- Offer terms keep changing or new fees appear near closing.
How to verify a real buyer in Florida before you sign
Legitimate buyers welcome verification. Here is how to confirm you're dealing with one, using the tools Florida gives you.
- Ask for proof of funds. A real cash buyer can produce a recent bank statement or a bank letter quickly. Verify it by calling the bank yourself, on a number you looked up.
- Confirm the business exists. Search the company's legal name on sunbiz.org. Check that it's active, that the address matches what they told you, and that the people you're dealing with are listed. Then look for a real website, a phone number that a person answers, and reviews.
- Check the title company, not just the buyer. Ask which title company will close. Look it up yourself, call its main number, and confirm it has your file. The Florida Department of Financial Services runs a public Licensee Search with fields for a person's first and last name and for an agency name, so you can look the agent up yourself.
- Insist on a written, plain-language contract you can take your time reading.
- Verify wire instructions by phone using a number you already trust, not one emailed to you.
- Get a second opinion. A quick comparable-sales check, a talk with a local agent, or a competing offer tells you whether the price is fair.
Why the Florida title company is your safety net
In a normal Florida cash sale, you never hand money or the deed to the buyer directly. The title company holds the buyer's deposit, clears the liens, records the deed and pays you. The law puts guard rails on how it does that.
- Your money sits in a regulated escrow account. Under section 626.8473, Florida Statutes, funds a title agency holds in trust must go right away into a Florida bank or credit union insured by the FDIC or the NCUSIF, in an escrow account, until the payout is properly authorized.
- The accounts get checked every month. The Department of Financial Services explains that rule 69O-186.009 requires every licensed title agent to keep a monthly reconciliation of every escrow account, backed by bank statements and a list of outstanding checks.
- The deposit goes to the title company, not the buyer. If a buyer wants the earnest money or any payment sent to them personally, that's a red flag.
That's why "close at a title company of your choice" is one of the best questions you can ask. A real buyer says yes without a pause.
Florida's foreclosure-rescue law, in plain words
If your home is in foreclosure, Florida gives you extra protection. Section 501.1377, Florida Statutes covers people who sell "rescue" help and buyers who take a homeowner's deed in a foreclosure-rescue deal.
- No pay before the work is done. A foreclosure-rescue consultant can't collect any payment until every service in the written agreement is finished.
- Three business days to cancel. You can cancel a rescue services agreement within 3 business days after signing, with no penalty. If you signed a foreclosure-rescue transaction (you sell the house and are promised a way to stay or buy it back), you can cancel until 5 p.m. on the 3rd business day after signing.
- The buyer must deal with the loan. In a foreclosure-rescue transaction, the buyer has to pay off or take over the loan in foreclosure, plus earlier liens the foreclosure wouldn't wipe out, at or before the transfer.
- Buy-back terms have a limit. If your repurchase price is more than 17 percent a year above what the buyer paid to acquire, improve, keep and hold the property, the law presumes the deal was unconscionable.
- Real penalties. Violations are treated as unfair and deceptive trade practices, with a penalty of up to $15,000 per violation.
A straight cash sale where you move out and get paid at closing isn't a rescue scheme. The danger is the "sign the deed to us and rent it back" pitch. If someone offers you that while you're behind on payments, read this law first and talk to a lawyer. Our guide to selling your house before a Florida foreclosure walks through the honest options.
What a legitimate buyer shows you: one of our houses
Talk is cheap, so here's what we show sellers. On our projects page you'll find houses we bought, photographed the day we got the keys and again when the work was done. One of them had been through a flood. The drywall was cut out two to four feet up every wall, there was black mold on the walls and ceilings, a hole in the ceiling, a green pool and a county notice taped to the door. We bought it exactly like that in August 2025, and the seller moved nothing.
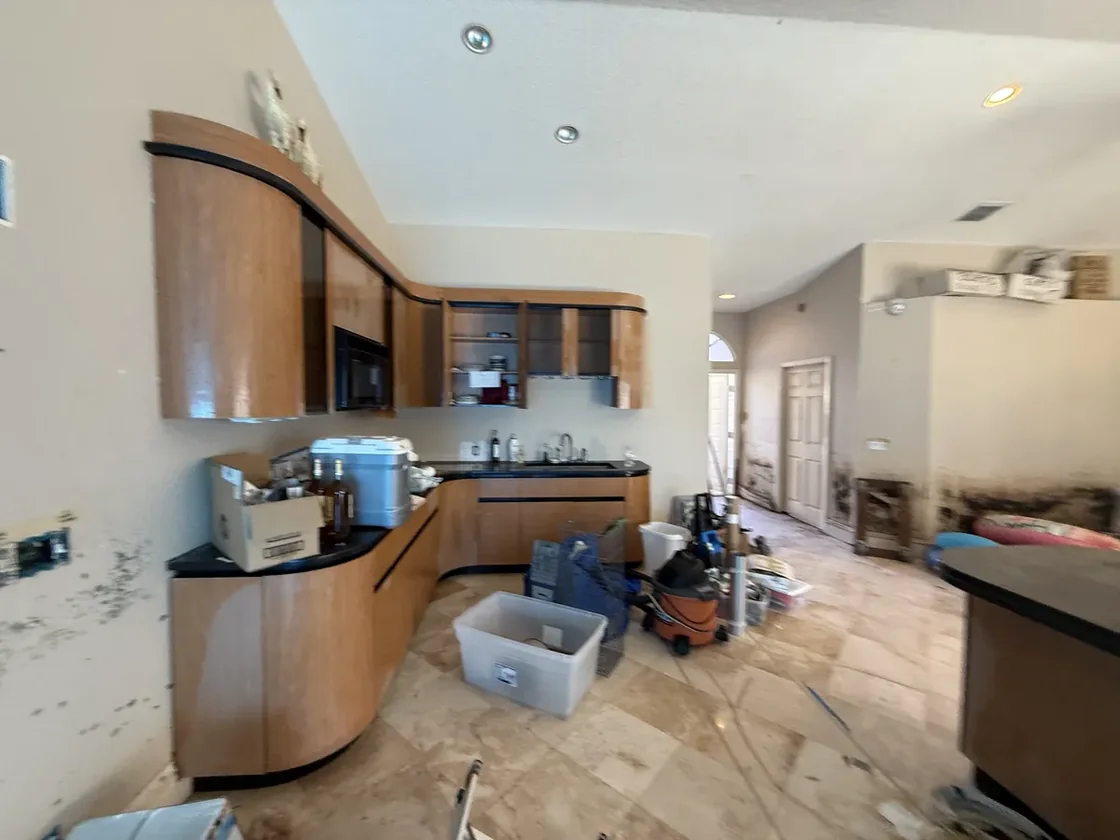
We took it back to the studs: new drywall and paint, a new kitchen, new floors, both bathrooms rebuilt and the pool resurfaced. The finished house sold in September 2026. That's the honest business model in one story. We pay cash for the house as it is, the repairs and the risk become ours, and that's why our offer sits below a fixed-up retail price. A buyer who can't show you anything like this, real houses with real before photos, deserves a few more questions.
When you talk to any cash buyer, ask to see this kind of record: photos taken the day they got the keys, photos of the finished house, and the date each sale closed. A company that really buys houses has these on file. A scammer has stock pictures or nothing at all.
Questions to ask any cash buyer
- What is your legal company name, and can I find it on sunbiz.org?
- Can you send proof of funds I can independently verify?
- Will you see the property before making a firm offer?
- Which licensed title company will handle closing, and can I pick my own?
- Where does the deposit go? (The answer should be the title company's escrow account.)
- How did you arrive at this offer price? Can I see the comparable sales?
- Are there any fees to me, ever? (The answer should be no.)
- Can you show me houses you've actually bought?
- Can I review the contract and take time before signing?
Your protections under the law
You have real safeguards, especially if you're behind on payments or facing foreclosure.
- The MARS Rule (Mortgage Assistance Relief Services). The FTC explains that it's illegal for a mortgage-relief company to charge you anything until it delivers a written offer from your lender and you accept it. Demands for upfront payment are a violation.
- Florida's foreclosure-rescue law. Section 501.1377 bans upfront payment for rescue services and gives you a short window to cancel, as described above.
- Title and escrow oversight. Closing through a licensed Florida title agent means a neutral party handles the deed and the money from a regulated escrow account.
- Where to report. File complaints at ReportFraud.ftc.gov, with the CFPB at consumerfinance.gov/complaint, and with the Florida Attorney General's office.
This article is general information, not legal advice. If a deal feels wrong, talk to a Florida real estate attorney before you sign anything or transfer your deed.
Want to see what an honest process looks like start to finish? Read how selling to a cash home buyer works and what to expect from a we buy houses company.
Frequently asked questions
Are 'we buy houses for cash' companies a scam?
No, not as a category. Many are legitimate investors who buy homes as-is and close quickly. But individual scammers do operate in the space, so you should verify proof of funds, confirm the business is registered, close through a licensed title or escrow company, and never pay an upfront fee.
Why do cash buyers offer less than market value?
Because you're trading price for speed, certainty, and convenience. Cash buyers estimate what the home will be worth after repairs, then subtract the repairs, holding costs, resale costs and profit. In exchange you avoid agent commissions, repairs, showings, and financing fall-through.
What's the biggest red flag of a fake cash buyer?
Any request for money up front. A real buyer never asks the seller to pay a deposit, application, or processing fee to receive an offer. Other major flags are refusing to show proof of funds, never seeing the home, asking you to sign over the deed early, and pressuring you to sign or wire money immediately.
How do I verify a cash home buyer in Florida is real?
Ask for proof of funds and verify it by calling the bank directly. Search the company on sunbiz.org. Insist on a written contract and a licensed title company for closing, and call that title company yourself to confirm it has your file. Legitimate buyers welcome this and answer plainly.
Is it safe to sell to a cash buyer if I'm in foreclosure in Florida?
It can be, but this is where equity-skimming scams concentrate. Never sign over your deed in exchange for a promise to rent the home back. Florida's foreclosure-rescue law, section 501.1377, bans upfront payment for rescue services and lets you cancel a rescue deal within 3 business days. Consider a real estate attorney first.
Where do I report a we-buy-houses scam?
Report to the FTC at ReportFraud.ftc.gov, to the Consumer Financial Protection Bureau at consumerfinance.gov/complaint, and to the Florida Attorney General's office. If you've already wired money, contact your bank immediately, fast action sometimes allows a recall.
Related
Sources
- Florida Statutes s. 501.1377: Violations involving homeowners during the course of residential foreclosure proceedings
- Florida Statutes s. 626.8473: Escrow; trust fund (title insurance agents)
- Florida Department of Financial Services: Title Insurance Agents compliance
- Florida Department of Financial Services: Licensee Search
- FTC Consumer Advice: Mortgage Relief Scams (MARS Rule)
- FTC Consumer Alert (April 2026): Could that mortgage relief offer be a scam?
- CFPB: Mortgage closing scams, how to protect yourself and your closing funds
- CFPB, FTC and States Announce Sweep Against Foreclosure Relief Scammers
- FTC: Report Fraud
- CFPB: Submit a Complaint
One step left
Get your number. Then decide.
Two minutes now. Your number in writing within 12 hours of our call.
P.S. You don't have to decide anything today. Get your number, compare it with what an agent would get you, then decide. Moving help is limited each month.Nothing to decide today. Get your number, compare it with an agent's, then decide. Moving help is limited each month.