 BeforeAfter
Home › Who we help › House needs repairs
Roof, foundation, fire or water damage, mold or code violations: repairs are our job, not yours.
Get cash early for a down payment, rent or your move.
All you have to do is pack. Or leave it all, we clear it out.
Subject to qualification. When you sell to us.
Advance deducted from your proceeds at closing. See if you qualify ↓
 Prefer to talk? Call or text (888) 260-1777¡Hablamos español!
If the repair bill is bigger than the cash and energy you have, sell as-is. Don't borrow to fix a house you're leaving. We buy houses with bad roofs, cracked foundations, fire and water damage, mold, code violations and years of clutter. You do no repairs and no cleaning. We price the repairs openly in a written cash offer within 12 hours, and we renovate the house ourselves.
Sell it exactly as it is today.
Our repair estimate is part of your written offer, so you see the number.
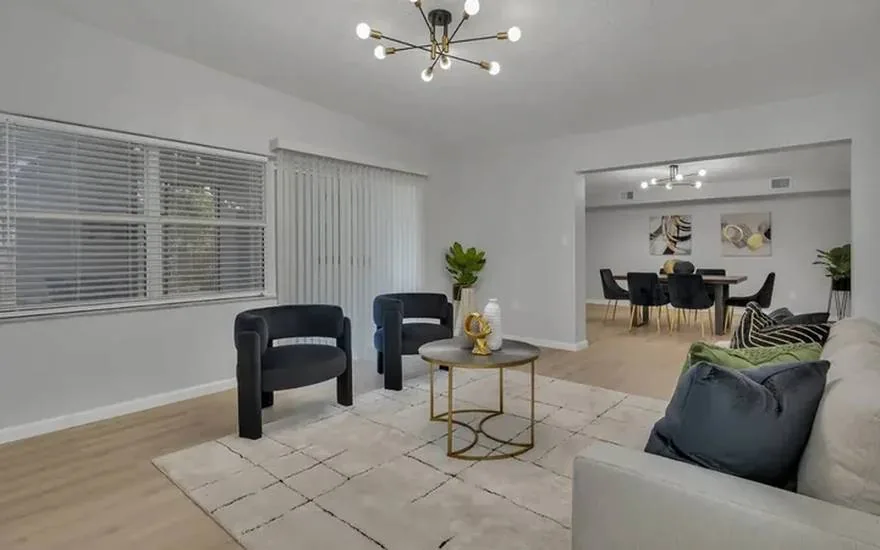
We fix it up and give it a second life. See our work below.
We're not contractors, inspectors or attorneys. If you want a second opinion on a repair, get a local quote. If you're unsure what you must disclose in your state, ask a real estate attorney.
Should you fix it up or sell it as-is? Here's the honest test. Fixing first only pays if you can cover the repairs in cash, wait out the work and the listing, and still net more than a cash sale after commissions and the buyer's credits. If any one of those is a no, selling as-is is usually the better path.
One more thing most people don't hear: anything you fix, we would have fixed ourselves, usually for less, because we renovate houses all the time. So a repair you pay retail for rarely comes back to you in the price. That's why we say leave it. If you're weighing a full renovation against a listing, our guide on how much you lose selling as-is walks through the trade-off in detail.
| Repair first, then list | Sell as-is to us | |
|---|---|---|
| Money upfront | You pay contractors before you sell | Nothing. We never ask sellers for money |
| Who takes the repair risk | You, including surprises mid-job | We do, after closing |
| Inspection and lender | Buyer's inspector and lender can still walk | No inspection contingency, no bank |
| Time | Weeks of work, then marketing, then a financed closing | Written offer in 12 hours, close in as fast as 7 days |
| Fees | Commission and closing costs come out of your price | No commissions, no fees, no closing costs to you |
| Price | Highest if everything goes right | Lower, shown with the math |
Will we buy a house with a bad roof, a cracked foundation or fire damage? Yes, all of these, and the ones below are the problems we see most. Guides: a house that needs a new roof, fire damage, code violations and a hoarder house.
Missing shingles, leaks, a sagging roofline or an insurer that wants it replaced before renewing. A new roof is one of the first things we budget for, so leave the tarps on.
Cracks you can fit a coin in, doors that won't close, a floor that slopes. Most buyers can't get a loan on a house like this; we don't need one, and we price in our own structural estimate.
A kitchen fire, a burst pipe, a flooded basement or storm damage that insurance didn't fully cover. We buy houses mid-claim and houses with no claim at all; tell us what happened and what's been done since.
Mold means there was moisture, so we look for the water source first and budget for both the fix and the cleanup. The EPA's guide to mold, moisture and your home says the key to mold control is moisture control, and that larger areas call for professional cleanup.
Open violations, fines, a stop-work order or an addition that was never permitted. We buy with the violations in place and resolve them after closing; bring any letters from the city, they help us price it right.
Rooms you can't walk through, a garage full to the door, things nobody has the heart to sort. Take what matters to you and leave the rest; cleanout is free if you qualify.
You get a written cash offer within 12 hours, with the comps behind it. No obligation, no pressure.
Hi, I'm Andy.
Real estate investor since 2021
I buy houses in any condition. Some need a full renovation. Others are ready to rent out as they are. Either way, I buy them for cash and then rent them out or sell them.
Because I pay cash, I don't wait on a bank. So I can buy in almost any situation: behind on payments, inherited, full of belongings or falling apart. My offer is honest: it reflects the house as it is, how fast you need to sell, and what it takes to resell it. I show you every number, and you pick the closing date.
I make money when I fix up and resell a house, so my price is lower than what a fixed-up house sells for. In return, I take on the repairs, the risk and the wait. I never push. And if you expect more than the comps support, I'll tell you honestly.
Andy, Founder & CEO
Not sure selling to me is your best option? Compare your options →
BeforeAfter
We don't make blind offers from the couch, and we don't lowball first and explain later. Here's the math we use, and we show it to you on the written offer.
Fixed-up value, minus repairs, minus holding and resale costs, minus our margin, equals your cash offer. Every line is on the sheet. If a number looks wrong to you, say so. We'd rather fix the estimate than lose the deal over a misunderstanding.
After the visit, the price only changes if we find something major you didn't mention, and then we show you what we found and explain the change in writing. We buy houses for cash; when a home isn't one we renovate, a trusted partner investor buys it on the same terms. Same offer sheet, same date.
You keep the price minus what's owed on the house. At closing, the title company pays off your mortgage and any liens or unpaid taxes from the sale, then pays you the rest. No commissions, no fees, no closing costs on your side. We never ask you for money, not for an inspection, not for a deposit, not for anything.
Our offer is lower than a fixed-up retail price. In exchange you skip repairs, commissions, showings and months of waiting. We show the math. If you want to see how that compares with listing the house in its current state, read cash offer vs. realtor or our page on selling a house as-is.
See your numberor call (888) 260-1777
As-is means you won't fix anything. It doesn't mean you can stay quiet about what you know. Your state likely has seller disclosure rules about known problems, and they apply to a cash sale too. We're not attorneys, so for your state's exact rules ask a real estate attorney or your closing agent. But the practical rule is simple: tell us what you know. It can't hurt your offer much, because we're already pricing in repairs, and it protects you after closing.
One federal rule applies everywhere. The EPA's page on real estate disclosures about potential lead hazards says sellers of homes built before 1978 must disclose any known lead-based paint, give the buyer a lead information pamphlet and allow a period for a lead inspection. The title company includes that paperwork with the contract, so you don't have to chase it.
If a previous owner, or you, added a room, finished a basement or redid the electrical without a permit, say so. We buy houses with unpermitted work all the time. We'll decide whether to permit it after the fact, redo it or remove it, and that cost goes on the repair line like everything else. What we can't do is find out at closing. See selling a house with unpermitted work.
None of it is required. All of it makes the offer firmer.
Send the address and a phone number, or call (888) 260-1777. We'll ask what's wrong with the house in your own words. No photos needed, though they help. Within 12 hours you get a written cash offer with the comps and the repair line behind it. Then one visit to confirm the condition. If the house is unsafe to walk through, we'll look from outside and work from what you tell us.
No obligation. If the number doesn't work for you, you've lost nothing but a phone call. See how it works. If the house has been sitting empty while you decide, selling a vacant house covers what that costs you each month.
Best if: you need to sell fast, the house needs work, or life got complicated.
Only with Easy Sale
Subject to qualification.
Best if: you are not in a rush and you are OK with showings.
The trade-off
Not sure which is better? On the call we'll tell you what your house would likely sell for on the market and what you'd keep each way. Then you decide.
No pressure
Proof of funds on request
No obligation until you sign
Title company or attorney
I had a great experience working with Sterling Home Offer. Their communication was excellent throughout the entire process, and they made everything simple and stress-free. The team was professional, responsive, and very easy to work with. I truly appreciated how smoothly everything went and would definitely recommend them to others!
If youve never been thru probate consider yourself lucky. Its a mess. Sterling actually knew what they were doing which is more than I can say for the first 2 companies I called. They worked with my attorney and didnt make it harder than it already was. ✨
Only if we find something major that wasn't mentioned, such as a foundation issue or an active leak you didn't know about. If that happens, we show you what we found and explain the change in writing, line by line. If you told us about a problem up front, it's already priced in and the number holds.
No. Anything you fix, we would have fixed ourselves, usually for less, and a retail repair rarely comes back in the price. See "Fix it up or sell as-is?" above.
No. The written offer comes from the address, the comps and what you tell us; one visit by our team confirms the condition. If you want your own inspection for your own comfort, you can order one, but we never ask you to pay for ours.
Tell us. We buy houses with unpermitted additions, basements and electrical work, and the cost to permit, redo or remove it goes on the repair line. See "Permits for past work" above.
Our offer is lower than what the house would sell for fully fixed up. The gap is the repair cost, our holding and resale costs and our margin, and we show each line. Against that, you skip paying for repairs, commissions, closing costs, showings and months of waiting. Our guide on how much you lose selling a house as-is walks through a worked comparison.
Yes. Mold means there has been water, so we budget for the water source and the cleanup, and for fire or water damage we ask what happened and whether there was a claim. See the Mold and Fire or water damage cards above.
Usually, yes. An uninsured house, an open code case or even a condemned house can still be sold; it just can't be sold to a buyer who needs a mortgage. We buy for cash, so that isn't a problem. We'll ask for any letters from the city or the insurer and price the work to bring the house back into compliance. If a house truly can't be bought, we'll tell you on the call.
General information, not legal, tax or financial advice.
One step left
Two minutes now. Your number in writing within 12 hours. Then it's your call.
P.S. You don't have to decide anything today. Get your number, compare it with what an agent would get you, then decide. Moving help is limited each month.Nothing to decide today. Get your number, compare it with an agent's, then decide. Moving help is limited each month.