Home › Blog › How Selling to a Cash Home Buyer Works: Full Guide
Cash Home Sale GuideHow Selling to a Cash Home Buyer Works, Step by Step
Selling to a cash home buyer means you accept an offer from someone who pays without a mortgage. You share your address, get a no-obligation offer, sign a purchase agreement, and let a title company verify ownership and clear any liens. Because there's no lender, appraisal, or loan underwriting, a cash sale can close within weeks instead of months, often with no repairs and no agent commission.
What a cash sale actually means
A cash sale is simple: the buyer has the full purchase price on hand and does not need a mortgage. That one fact changes everything downstream. There is no loan application, no underwriting, and no lender-required appraisal, so the steps that cause most traditional deals to stall or fall apart are removed.
A direct cash buyer like Sterling Home Offer is the buyer itself, not an agent listing your home or a wholesaler shopping it to a list. That means the offer you accept is the company's own commitment to purchase, and you are not paying a commission for the privilege. Most cash buyers purchase the home as-is, in its current condition, so you skip repairs, cleaning, and staging.
The step-by-step process, from first contact to closing
Every reputable cash purchase follows roughly the same path. Here is the full sequence:
- 1. First contact. You reach out with basic details, the property address, its condition, and your ideal timeline. This is a short form or a phone call, not a credit check.
- 2. Offer. A direct buyer reviews the home and local market and returns a no-obligation cash offer, often within 24 hours. Nothing is binding at this stage.
- 3. Review and decide. You compare the number and terms against your alternatives. A good buyer will explain how the figure was reached. You are free to walk away.
- 4. Purchase agreement. If you accept, both sides sign a written purchase agreement that sets the price, the closing date, and any conditions. Until this is signed, nothing is locked in.
- 5. Title and due diligence. A title company or real estate attorney runs a title search to confirm you are the legal owner and that there are no liens, judgments, or claims that would block the sale.
- 6. Closing day. You sign the deed transferring ownership, the settlement agent disburses the funds (usually by wire), and the documents are recorded with the county. You get paid.
A cash buyer may still do a walk-through or quick inspection to confirm condition, but in an as-is sale this rarely changes the price unless something major was undisclosed.
See your number. Then decide.
You get a written cash offer within 12 hours of our call, with the comps behind it. No obligation, no pressure.
- No fees or commissions
- Sold as-is
- You pick the date
How long does a cash sale take?
Because the lender steps are gone, the timeline collapses to whatever the title work and your own schedule require. With us, closing usually takes 14 to 30 days, and the date is yours to pick. The biggest variable is usually the title search, clearing an old lien, an estate, or a probate matter can add time.
One advantage of a direct buyer is flexibility: if you need to close fast, that is possible, but if you need to wait, say, until probate finishes or you've found your next place, a good buyer can hold the closing date for you.
Why does a financed sale take so long? Most of the time goes to the buyer's loan: underwriting, the appraisal, and the lender's paperwork (HomeLight). Federal rules also make the lender give the buyer the Closing Disclosure at least three business days before closing (CFPB), so any late change to the loan can push the date back. A cash buyer skips the loan part of it.
| Step | Traditional financed sale | Cash sale |
|---|---|---|
| Loan underwriting | Takes most of the closing period | None |
| Lender appraisal | Required | Not required |
| Title search | Needed | Needed |
| Typical time to close | Set by the lender's schedule | 14 to 30 days with us |
| Risk of a loan delay or fall-through | Real | None |
The paperwork you'll see
A cash sale uses fewer documents than a financed one, because there is no loan note, no mortgage, and no lender disclosures. The core paperwork is:
- Purchase agreement. The contract that sets price, closing date, and conditions, signed by both parties.
- Title search and title commitment. Confirms clear ownership and surfaces any liens or claims that must be cleared first.
- Settlement statement. An itemized list of the money changing hands at closing, what you receive and any costs deducted.
- Deed. The legal document that transfers ownership from you to the buyer. You sign this at closing.
- Identity and payoff documents. ID for the notary, plus any mortgage payoff or lien-release statements if you still owe on the home.
A neutral third party, a title company, escrow company, or closing attorney, typically prepares these, holds any deposit, and records the deed with the county after closing.
What changes when the house is in Florida
The steps above work the same way anywhere in the state, but Florida adds a few rules and numbers of its own. Knowing them ahead of time means no surprises on the settlement statement.
- Cash sales are common here. Of the 20,537 single-family homes sold in Florida in September 2026, 5,743 were paid for in cash, more than one in four (Florida Realtors). Selling without a lender is an ordinary sale in this state, not an odd one.
- The deed tax. Florida charges a documentary stamp tax on the deed of 70 cents for each $100 of the price (s. 201.02, Florida Statutes). On a $300,000 house that's $2,100. The purchase agreement says which side pays it, so read that line before you sign.
- The flood disclosure. A Florida seller must give the buyer a written flood disclosure at or before the time the contract is signed (s. 689.302). It asks whether you know of flooding that damaged the house while you owned it, whether you filed a flood insurance claim, and whether you got help for flood damage, such as FEMA aid. It applies to an as-is cash sale too: as-is means you don't fix things, not that you leave things out.
- An inherited house. If the will gives the personal representative a power to sell, the house can be sold without the court approving the sale (s. 733.613). Our inherited house page walks through it.
Who pays what
In a traditional sale, the seller usually pays the agents' commission, part of the closing costs, and often repairs and prep before listing. A direct cash sale is structured to remove most of that:
- No agent commission. You are selling directly to the buyer, so there is no listing or buyer's-agent commission coming out of your proceeds.
- No repair or prep costs. As-is means you don't pay to fix, clean, or stage anything.
- Standard closing costs. Reputable direct buyers typically cover the standard closing costs of the purchase. Sterling Home Offer covers standard closing costs and charges no fees to the seller.
- What may still be yours. Anything tied to your existing ownership, for example, paying off the remaining mortgage balance or settling a lien, comes out of your proceeds, because that debt is yours, not the buyer's.
Because cost conventions vary by state and even by region, ask your buyer to put in writing exactly which costs they cover. A clear written breakdown is a sign you're dealing with a transparent buyer.
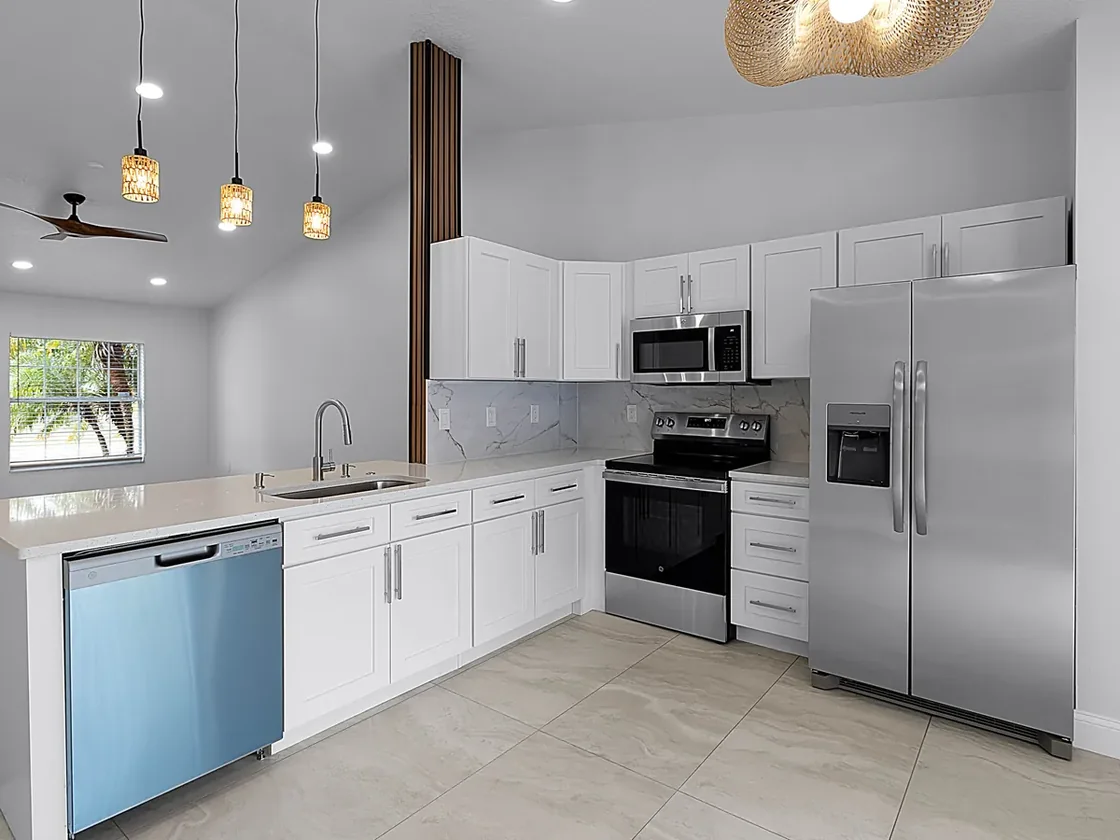
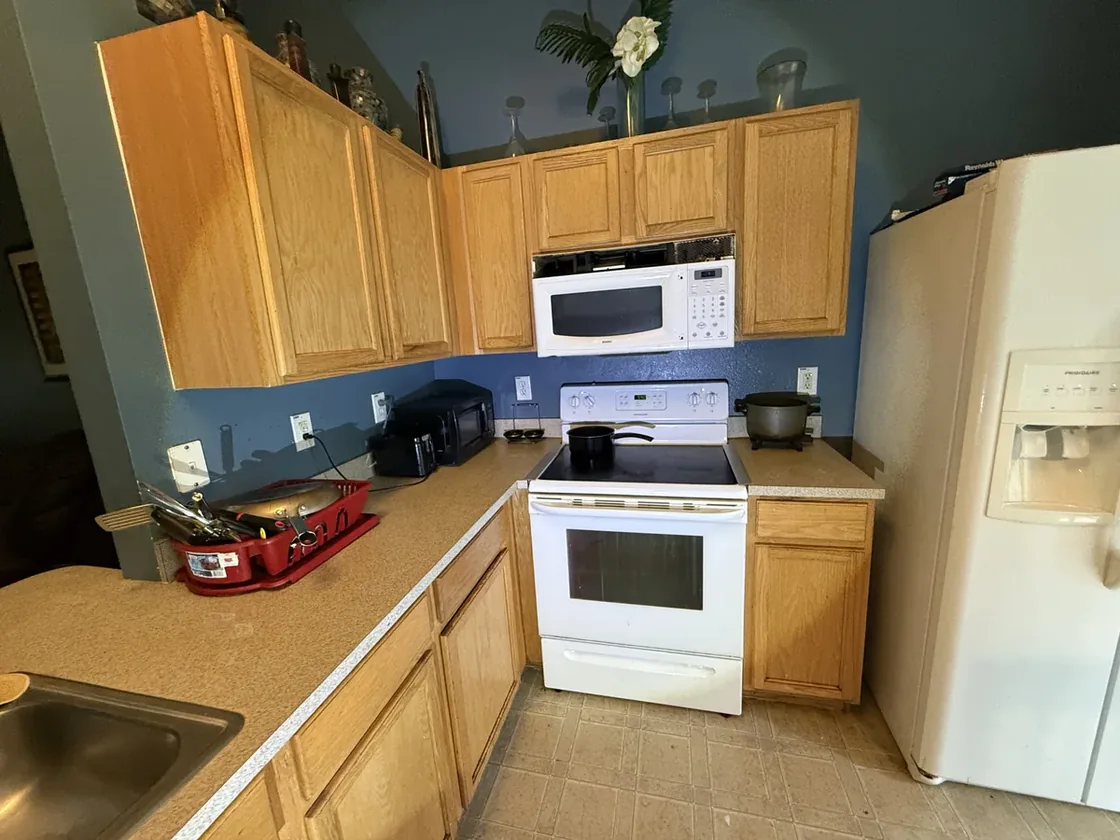
From our deals. One house we bought still had a family living in it. Inside it was dated but working: dark walls, oak cabinets, carpet, and a garage packed to the door. The sellers didn't paint, clear the garage or fix anything. After closing we did the work ourselves: full interior paint, new floors, a new kitchen with a wood-slat peninsula, new bathrooms and new lights, with the garage cleared and the outside painted. Those repair bills were ours, not theirs. You can see more of the houses we've bought as-is on our projects page.
How to protect yourself
Cash sales are fast, which is good, but speed is no excuse for skipping basic safeguards:
- Get the offer and cost coverage in writing. Nothing should be binding until a written purchase agreement is signed, and you should be able to read it before you sign.
- Use a neutral closing agent. A title company or attorney protects both sides and confirms title is clear before money moves.
- Verify wire instructions by phone. Scammers send fake last-minute changes to wiring instructions to divert closing money (CFPB). Confirm any wire details with the closing agent using a phone number you looked up yourself, not one emailed to you.
- Don't feel pressured. A no-obligation offer means exactly that. A buyer who rushes or pressures you is a red flag.
Comparing a local cash buyer with an online iBuyer? See cash offer vs. iBuyer (Opendoor and Offerpad) for how fees, repair deductions and eligibility differ.
Is a cash sale the right call for you?
Be honest with yourself about the trade. A cash offer for a house that needs work is usually lower than what the same house might bring after repairs and a full listing, because the buyer takes on the repairs, the holding costs and the risk. What you get back is speed, certainty and no work on your side. To see how that lower number is worked out, read what percentage cash home buyers pay.
A cash sale tends to make sense when the house needs repairs you can't or don't want to pay for, when you've inherited a place you don't plan to live in, when payments or taxes are falling behind, or when you simply need a fixed date. If the house is in good shape and you have months to wait, listing with an agent may net you more. Get a cash number anyway and compare it with what an agent tells you, after commission, repairs and the months of carrying costs. Then pick the road that leaves you better off.
This article is general information, not legal, tax or financial advice. Florida statutes and county practice change, and every property is different. Confirm your situation with a licensed Florida attorney or tax professional before making decisions about your home.
Frequently asked questions
Do I have to make repairs before selling for cash?
No. Direct cash buyers purchase homes as-is, in any condition. You don't pay for repairs, cleaning, or staging, the buyer factors the home's condition into the offer instead.
How fast can a cash sale close?
With us, closing usually takes 14 to 30 days, and it can be faster when the title is clean. The main variable is title work; clearing an old lien, an estate, or probate can add time. We break the steps down day by day in how fast you can sell a house for cash. A flexible buyer can also wait if you need more time.
Is the first offer binding?
No. A no-obligation cash offer is not binding. Nothing is locked in until both parties sign a written purchase agreement, and you are free to review, negotiate, or decline before that point.
Who pays the closing costs in a cash sale?
In a direct cash sale, the buyer typically covers the standard closing costs and charges the seller no fees or commission. Debts tied to your ownership, like a remaining mortgage balance or a lien, are paid from your proceeds. Always get the cost breakdown in writing.
Can I sell a house that still has a mortgage on it?
Yes. At closing, the settlement agent uses the sale proceeds to pay off your remaining loan balance first, and you receive whatever is left. The title company handles the payoff and lien release as part of the closing.
What paperwork do I need to sell to a cash buyer?
The essentials are a signed purchase agreement, a clear title (verified by a title search), a settlement statement, and the deed you sign at closing. You'll also need a valid ID for the notary and any mortgage payoff statements if you still owe on the home.
Related
Sources
- CFPB, What to expect in the closing process
- CFPB, Review documents before closing
- HomeLight, How long does it take to close on a house with cash?
- Florida Realtors, September 2026 single-family market summary (PDF)
- CFPB, What is a Closing Disclosure?
- CFPB, Mortgage closing scams
- Florida Statutes s. 201.02, documentary stamp tax on deeds
- Florida Statutes s. 689.302, flood disclosure
- Florida Statutes s. 733.613, sale of estate real property
One step left
Get your number. Then decide.
Two minutes now. Your number in writing within 12 hours of our call.
P.S. You don't have to decide anything today. Get your number, compare it with what an agent would get you, then decide. Moving help is limited each month.Nothing to decide today. Get your number, compare it with an agent's, then decide. Moving help is limited each month.