Selling a House Fast in Fort Myers or Cape Coral, Florida: What Actually Works in 2026
A few years ago, selling a house in Fort Myers or Cape Coral fast was easy: you put a sign in the yard and picked between offers by the weekend. That market is gone. Today Southwest Florida has plenty of homes for sale, buyers who negotiate hard, and a new gatekeeper nobody talks about enough: the insurance company. If you need to sell quickly, because of a move, a divorce, an inherited house, payments you are tired of carrying, or simply one storm season too many, the playbook matters more than it has in a decade. This guide covers why sales stall here, the two problems that quietly turn houses into cash-only houses, what waiting actually costs, and how a fast as-is sale works when speed and certainty are the priority.
Key highlights
- Southwest Florida is a buyer-leaning market now. More inventory and slower financed sales mean "fast" takes a plan, not a sign in the yard.
- Insurance is the new deal-breaker. A financed buyer cannot close without a bindable policy, so an aging roof or an open damage history can quietly make your house cash-only.
- Hurricane-era history follows the house: disclose honestly, but you do not have to finish the repairs to sell.
- Every month of waiting has a price tag here: insurance, taxes, upkeep, and a market that is not rushing to bail you out.
- An as-is cash sale skips repairs, cleanout, showings and financing, and closes in weeks on the date you pick.
The short answer
Yes, you can still sell a Fort Myers or Cape Coral house fast in 2026, but only by one of two honest routes. Route one: list it priced for today's market, not 2022's, in condition an insurer will accept, and be ready for the financed buyer's loan, appraisal and insurance steps to set your timeline. Route two: sell as-is to a cash buyer, where the offer comes in about a day, no lender or insurer has a vote, and the closing lands in as little as two to three weeks. Everything else, waiting for the old market to return, testing a high price "just to see", relisting after a failed deal, is the slow path wearing a fast costume. The rest of this guide is about choosing between the two real routes with your eyes open.
Why Southwest Florida sales stall in 2026
The boom years pulled thousands of new listings, new builds and investor flips into Lee County, and the buyer pool that used to absorb them has thinned: higher rates, higher insurance, and snowbirds doing more math than they used to. The result is simple supply and demand. Houses sit longer, buyers ask for concessions, and the financed offer you accept in week two can still fall apart in week six over an appraisal, a four-point inspection, or a policy that will not bind.
None of that means your house cannot sell. It means the market no longer forgives the two problems that Southwest Florida specializes in, and both of them wear insurance badges.
Insurance: the deal-killer nobody puts in the listing
Here is the chain reaction that kills financed sales in Fort Myers and Cape Coral. A buyer with a mortgage must carry homeowners insurance. Florida insurers, burned by storm years and litigation, have become picky: they scrutinize the roof's age, the wiring, the plumbing, past claims, and in flood zones the lender will require flood coverage on top. If the policy will not bind, or the quote lands somewhere painful, the buyer walks, often deep into the deal, after you have already turned down other offers.
The roof is the classic version. Insurers commonly balk at aging shingle roofs, and replacing one costs serious money you may not want to spend on a house you are leaving. The moment insurance becomes the obstacle, your real buyer pool is no longer "everyone on Zillow". It is buyers who do not need a lender or an insurer's permission: cash.
The quiet rule of today's SWFL market: any house an insurer does not like, because of the roof, the panel, the claims history, or unrepaired damage, is effectively a cash-only house, no matter how it is listed.
Sellers often discover this in week five of a financed deal. It is cheaper to know it on day one.
The hurricane-era house
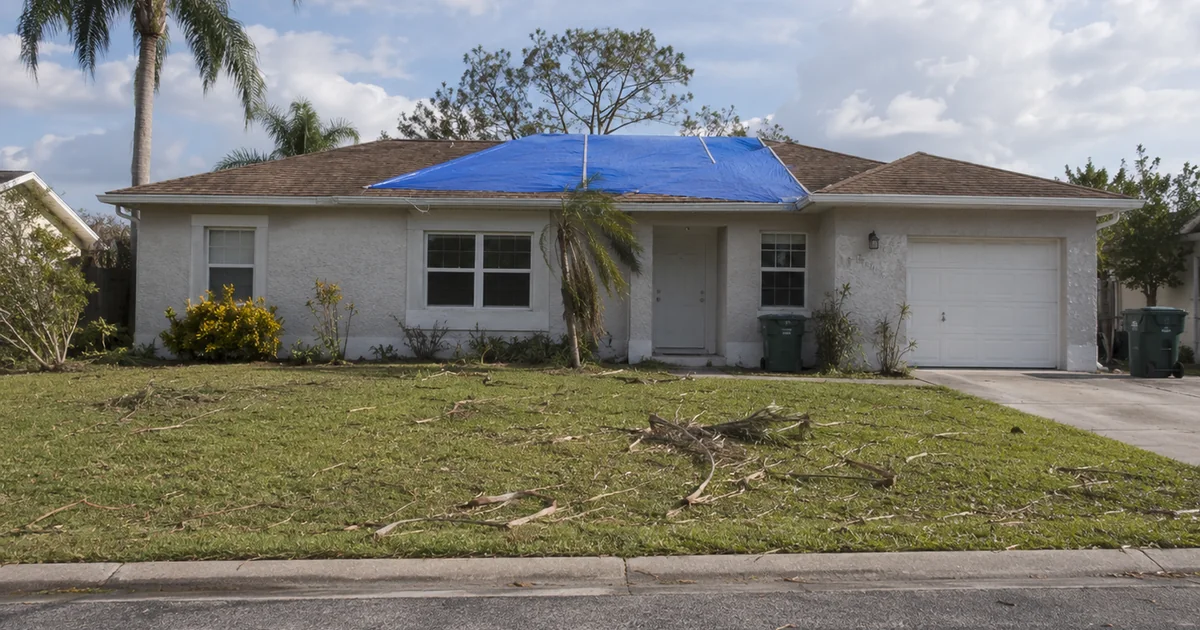
Fort Myers and Cape Coral carry the memory of the recent storm years in their housing stock: houses repaired fully, houses repaired halfway, houses where the contractor took the deposit and vanished, and houses where the owner simply ran out of fight. If yours is one of them, two facts matter.
First, disclosure is not optional. Florida requires sellers to disclose known material problems, and known flood damage and claims belong in that conversation. Honesty here is not just legal safety; it is what keeps a deal from collapsing later when the four-point inspection tells the story anyway.
Second, disclosure does not mean repair. You are allowed to sell the house exactly as it stands, tarp, permits half-pulled, materials in the garage. What you cannot easily do is sell that house to a financed buyer, because their lender and insurer will both say no. This is the exact situation as-is cash buyers exist for, and we wrote a full guide on it: selling a hurricane-damaged house as-is in Florida. If the insurance bill itself is what is pushing you out, this one is for you: selling when you can no longer afford Florida insurance.
What waiting really costs here
"We'll wait for a better market" is a plan with a monthly invoice in Southwest Florida. While the house waits, you keep paying insurance that is priced for the risk, property taxes, utilities, lawn and pool care so the neighbors and code enforcement stay calm, and, on a vacant house, an insurer that may restrict coverage precisely when the house is most exposed. Hurricane season adds its own tax: every June-to-November that passes is another spin of the wheel with your equity on the table. Add it up over six or nine months of "waiting to see", and the better market has to improve by a serious margin just to break even, in a market that is currently leaning the other way.
Your options, side by side
For a Fort Myers or Cape Coral seller who values speed, the realistic menu looks like this:
| Your option | Best when | The trade-off |
|---|---|---|
| Fix up and list with an agent | The house is insurer-friendly (newer roof, no open damage) and you can wait out a financed buyer | Repair money up front, showings, and a timeline set by the buyer's loan, appraisal and policy, in a market with plenty of competition |
| List as-is with an agent | The house is dated but insurable, and you can accept financed-buyer renegotiation | Inspections still happen, insurers still vote, and rough houses tend to sit, then sell to investors anyway, minus commission |
| Sell as-is for cash | The roof, the damage history, the timeline or the distance makes a financed sale unrealistic, or you simply want it done | The price reflects the condition and the work remaining; in exchange, no repairs, no cleanout, no showings, no financing risk, closing in weeks |
| Wait for a better market | You genuinely do not need to sell and can fund the carrying costs indefinitely | Insurance, taxes and upkeep every month, another hurricane season every year, and no guarantee the market cooperates |
How a fast as-is cash sale works in Lee County
The mechanics are refreshingly boring. You describe the house honestly, condition, damage history and all, and get a written cash offer, typically within about 24 hours. If you accept, a title company in Lee County takes over: confirming the title, clearing any liens or back taxes out of the proceeds at closing, and preparing the deed. There is no lender, so there is no appraisal, no financing contingency, and no insurance underwriter deciding your fate in week five. The closing lands on the date you pick, as soon as roughly two to three weeks out if the title is clean, or later if you need time to move. You take the belongings you want and leave the rest, cleanout included in the deal. What selling as-is really covers, in plain words, is here: what selling a house as-is actually means, and the honest timeline math is here: how fast a cash sale really closes.
How Sterling Home Offer helps
We buy houses for cash across Southwest Florida, Fort Myers, Cape Coral, North Fort Myers, Lehigh Acres and the surrounding Lee County communities, and difficult-to-finance houses are our normal workload, not the exception. Here is our promise, in writing. A no-obligation cash offer within about 24 hours, based on the house's real condition and real area sales, not a teaser number that shrinks at the closing table. Strictly as-is: no repairs, no cleanout, old roof and storm history welcome, disclosed and priced honestly. No agent commissions and no fees; the offer is the number. And your timeline is the timeline: two-something weeks when the paperwork allows and you are in a hurry, or parked politely until your move, your probate, or your divorce decree is ready. If the house is inherited, this companion guide walks the Florida specifics: selling an inherited house in Florida.
The bottom line
Selling fast in Fort Myers or Cape Coral in 2026 is not about luck, it is about matching the route to the house. An insurer-friendly house priced for today's market can still do fine with an agent, on the market's schedule. A house with an aging roof, a storm story, a flood zone address, or a seller who needs certainty more than the last dollar has a cleaner route: an as-is cash sale that closes in weeks, with no lender and no insurance underwriter holding the pen. Either way, the worst plan in Southwest Florida is drifting: the carrying costs are real, hurricane season is annual, and the house is not getting younger while you decide.
Need to sell fast in Fort Myers or Cape Coral?
We buy Southwest Florida houses as-is for cash: old roofs, storm histories and full garages welcome. No repairs, no fees, no showings. Get a no-obligation cash offer in 24 hours and pick your closing date.
Get my cash offer or call (888) 480-5544Fort Myers and Cape Coral seller FAQs
How fast can I actually sell a house in Fort Myers or Cape Coral?
With a cash buyer, the timeline is driven by paperwork, not by the market: an offer within about a day, and a closing in as little as two to three weeks once the title company confirms the title is clean. A financed sale is different math: time to prepare and list, time on a market with plenty of competing inventory, then a month or more of the buyer's loan, appraisal and insurance steps, any of which can restart the clock.
Do I have to repair hurricane damage before selling?
No. You must disclose known damage and past claims honestly, but you do not have to repair anything to sell as-is to a cash buyer. Unrepaired or partially repaired houses are hard to sell to financed buyers because lenders and insurers balk, which is exactly why cash exists for this situation. The price will reflect the remaining work, and in exchange you skip the contractor phase entirely.
My roof is old and insurers do not like it. Can I still sell?
Yes, but understand what the roof does to your buyer pool. In Florida, insurers commonly refuse or surcharge policies on aging roofs, and a financed buyer cannot close without insurance. That quietly turns an older-roof house into a cash-only house, no matter how it is listed. You can replace the roof before listing, or sell as-is to a cash buyer and let the price reflect the roof instead of fronting the cost yourself.
The house is in a flood zone, or flooded before. Does that end a normal sale?
It does not end it, but it reshapes it. Florida requires sellers to disclose known flood damage and claims. Buyers in flood zones face mandatory flood insurance if they finance, and that cost turns some of them away late in the process. Cash buyers price the flood reality in up front, which is often less painful than losing a financed buyer in week five.
Is 2026 a bad time to sell in Cape Coral or Fort Myers?
It is a slower, buyer-leaning market than the frenzy years: more homes for sale, more negotiating, longer waits for financed offers. That does not mean you cannot sell. It means the fast paths matter more: pricing realistically, or selling as-is for cash if speed and certainty are the priority. Waiting for the old market to come back is a strategy with carrying costs attached.
The house is full of furniture and belongings. Do I need to clear it out first?
Not for an as-is cash sale. Take what you want to keep and leave the rest, furniture included; the buyer handles the cleanout after closing. This matters for Southwest Florida sellers who are out of state, handling an inherited house, or leaving after one storm season too many and do not want to spend weeks emptying rooms.
This article is general information, not legal, tax or insurance advice. Florida disclosure requirements, insurance underwriting practices and market conditions change over time, and every sale is different. Confirm your situation with licensed Florida professionals before making decisions about your home.